A New Era in Corporate Tax
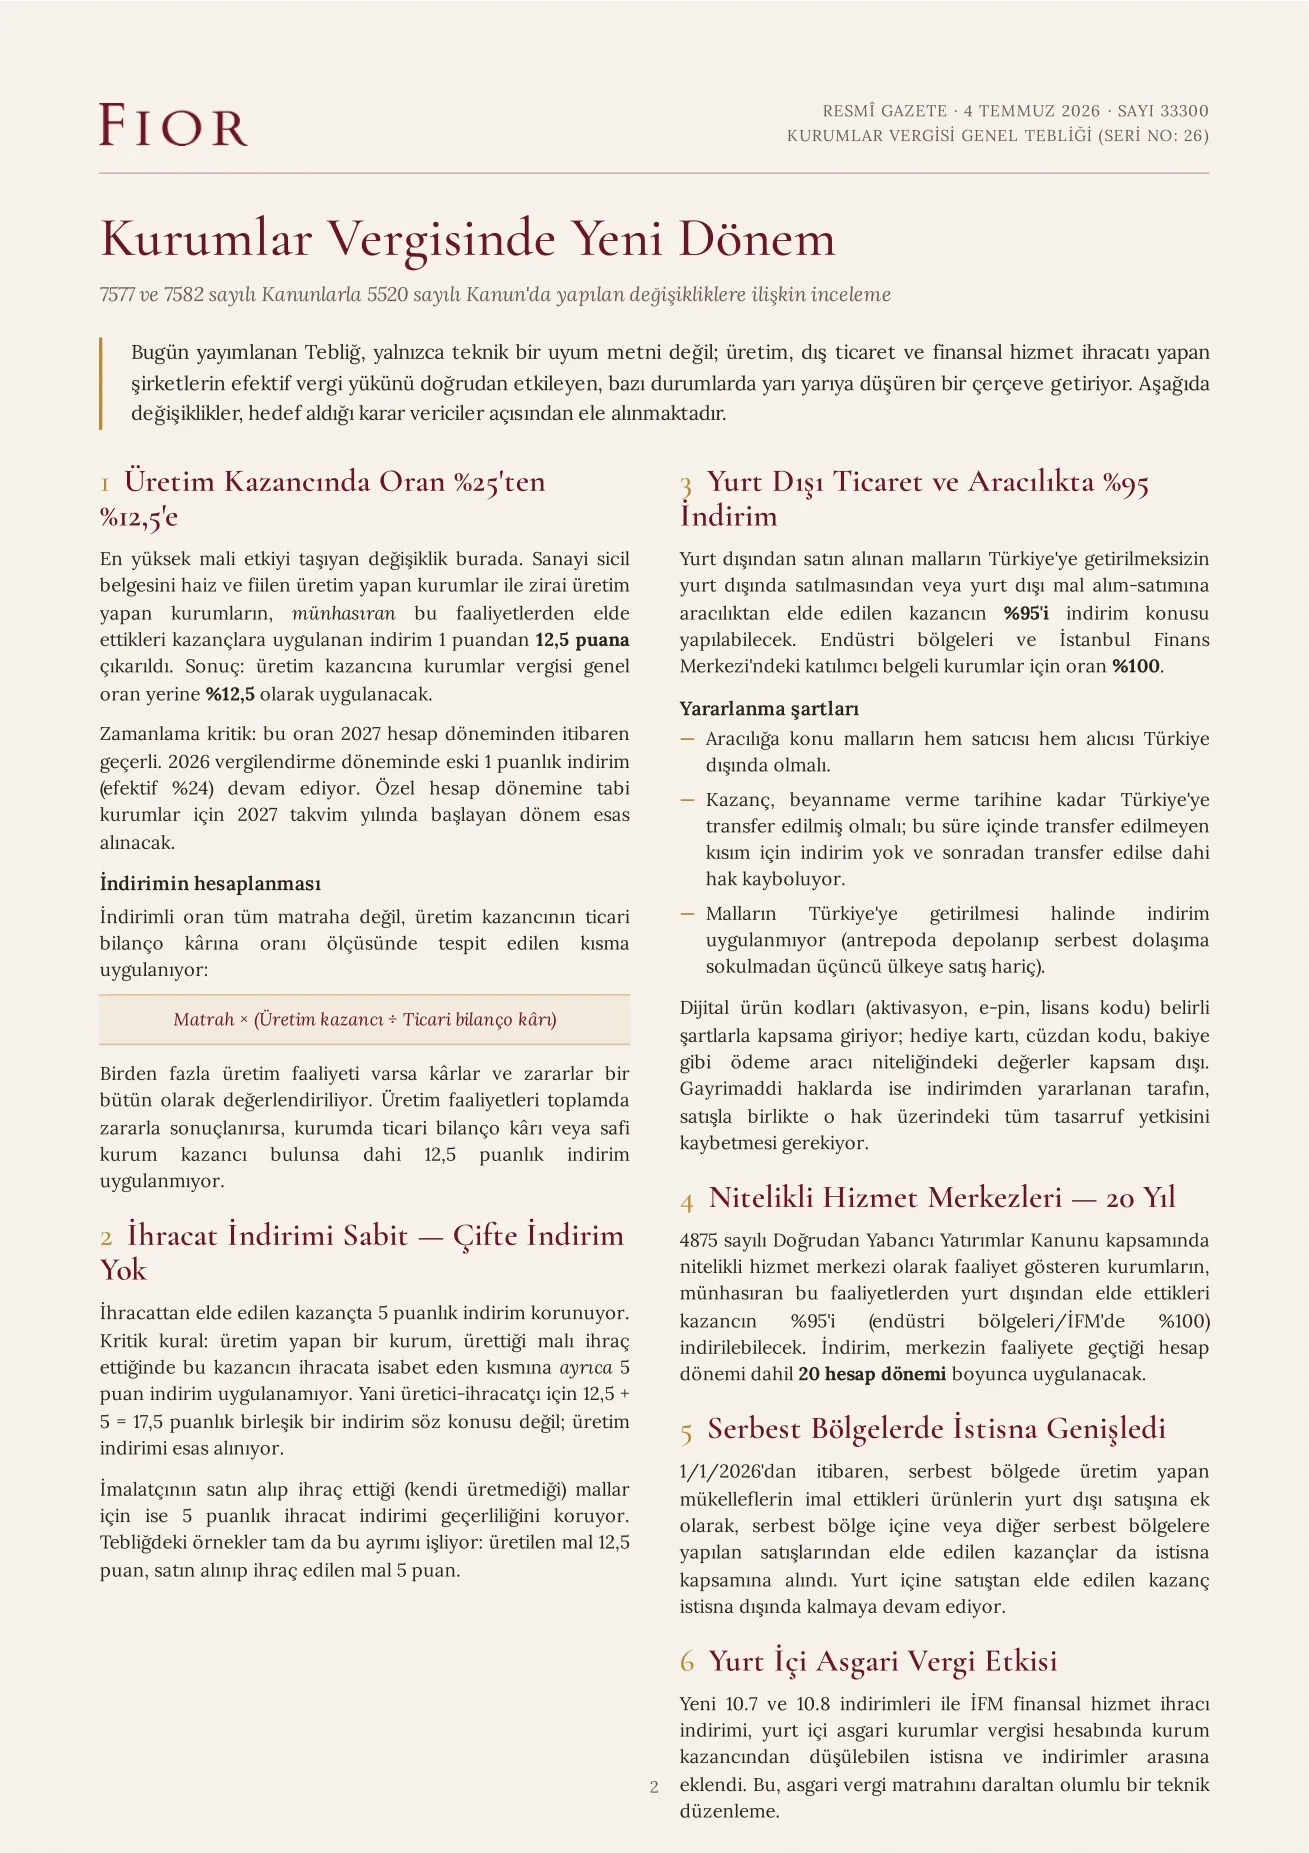
Corporate Tax General Communiqué (Serial No. 26) was published in the Official Gazette of 4 July 2026 (No. 33300). It sets the procedure for the amendments to Law No. 5520 made by Laws No. 7577 and 7582: not a technical alignment text, but a framework that cuts the tax burden on production, foreign trade and financial-services exports — in some cases by half.
The costliest change sits on production income. For companies that hold an industrial-registry certificate and actually manufacture, and for those engaged in agricultural production, the reduction on income exclusively from those activities rises from 1 point to 12.5 points: a 12.5 per cent rate in place of the general rate. It applies from the 2027 accounting period; in 2026 the old one-point reduction (effective 24 per cent) remains. The relief is not applied to the whole tax base, but in proportion to production income over commercial-balance-sheet profit; if production activities as a whole make a loss, there is no 12.5-point reduction.
The five-point export reduction is kept, but there is no stacking: a producer-exporter cannot combine 12.5 + 5; the production reduction prevails. Goods bought in and re-exported still take the five-point export relief. Ninety-five per cent of income from goods bought abroad and sold abroad without entering Türkiye, or from intermediating such trades, may be deducted (100 per cent in industrial zones and the Istanbul Finance Centre); the profit must be remitted to Türkiye by the filing date. Qualified service centres may deduct 95 per cent of their foreign-source income for 20 accounting periods. From 1 January 2026, income from sales of goods manufactured in a free zone into that zone or to other free zones is also exempt.
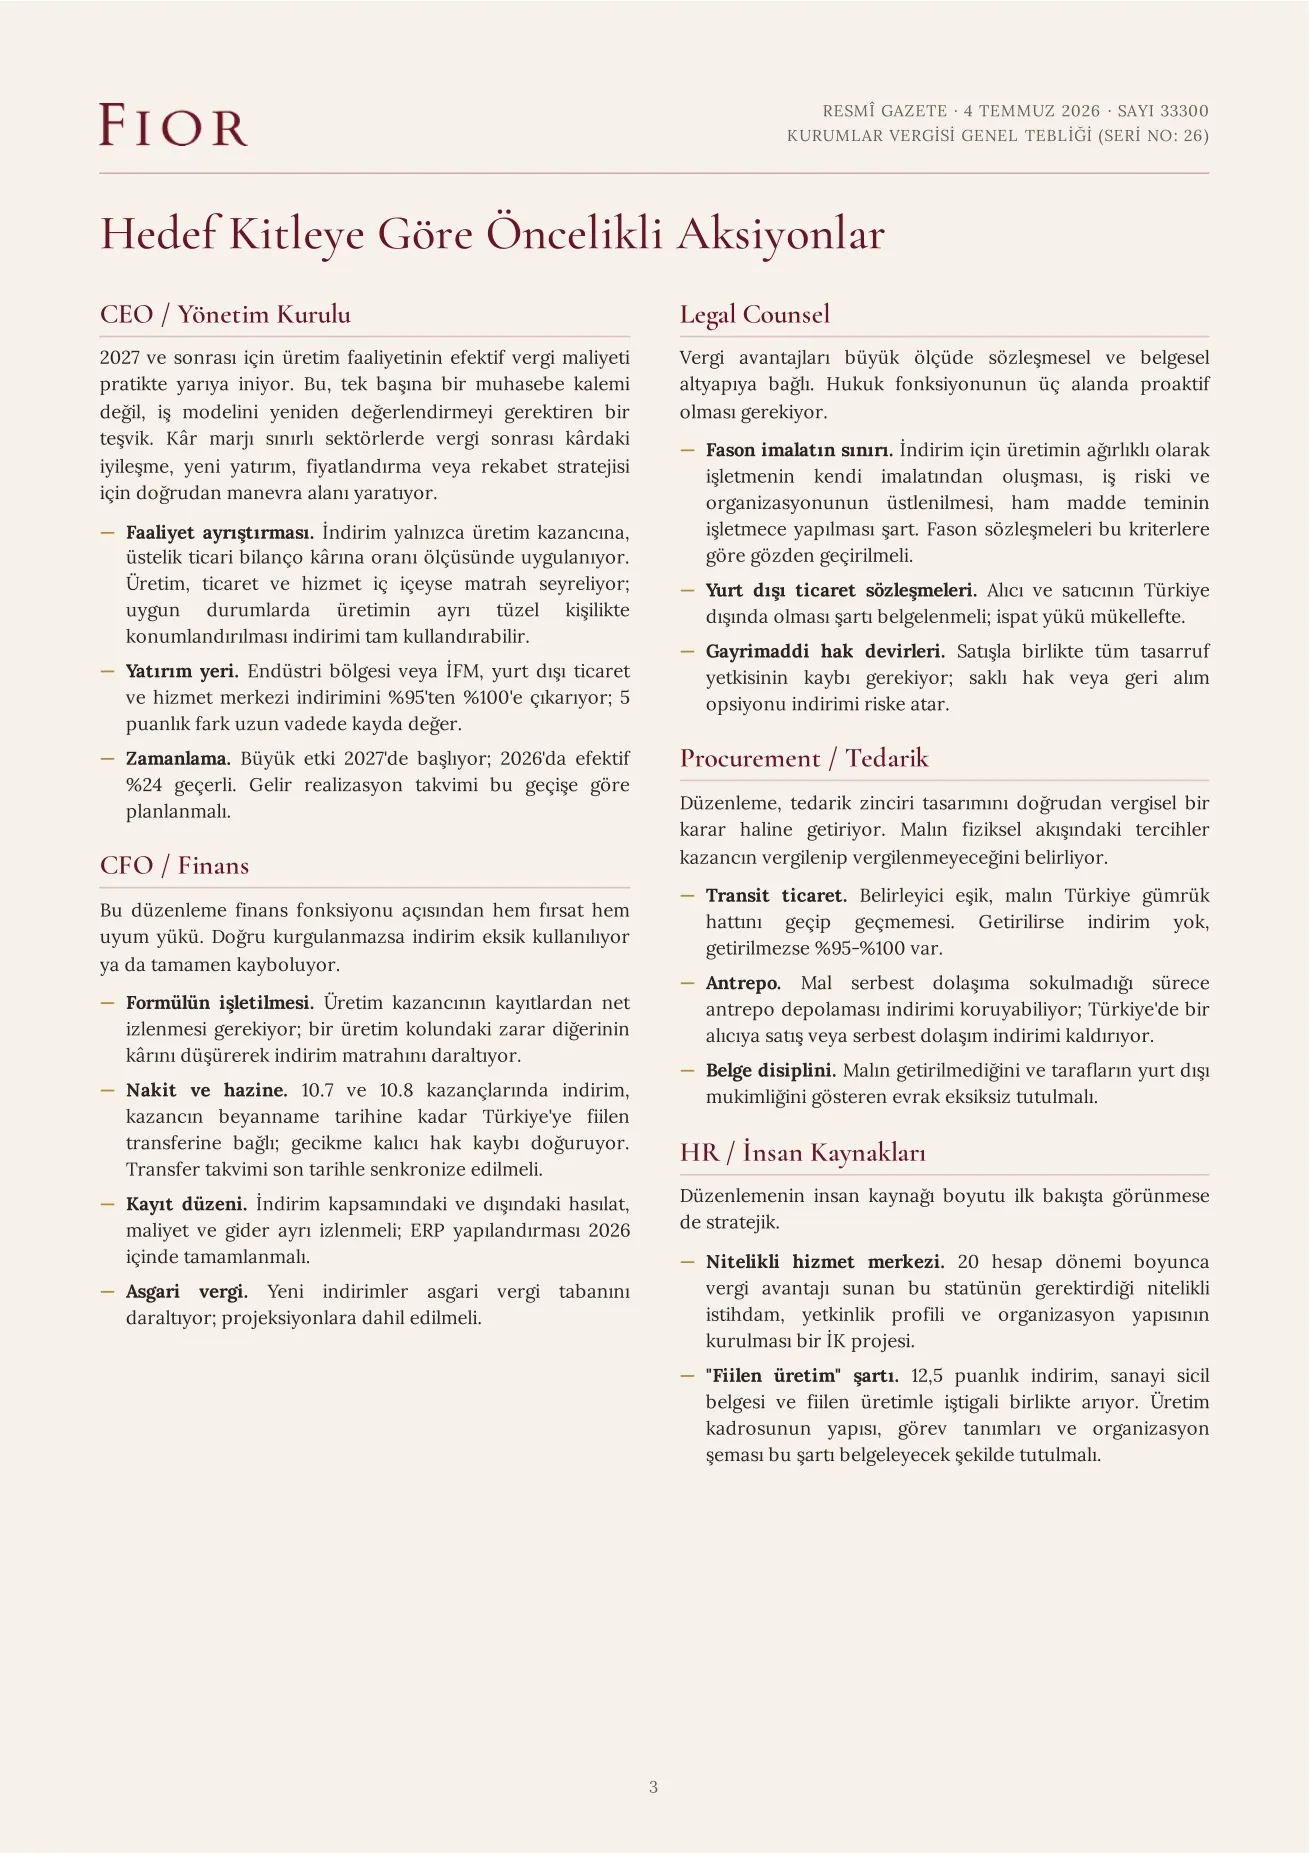
The new 10.7 and 10.8 deductions and the IFC financial-services export deduction are now among the items that may be subtracted in the domestic minimum corporate-tax calculation. Whether the relief is available turns on the boundary of contract manufacturing, the separation of activities, contractual and documentary discipline, and the transfer calendar. Our review is below.