Offset of Income Tax Withheld from Athletes’ Wages
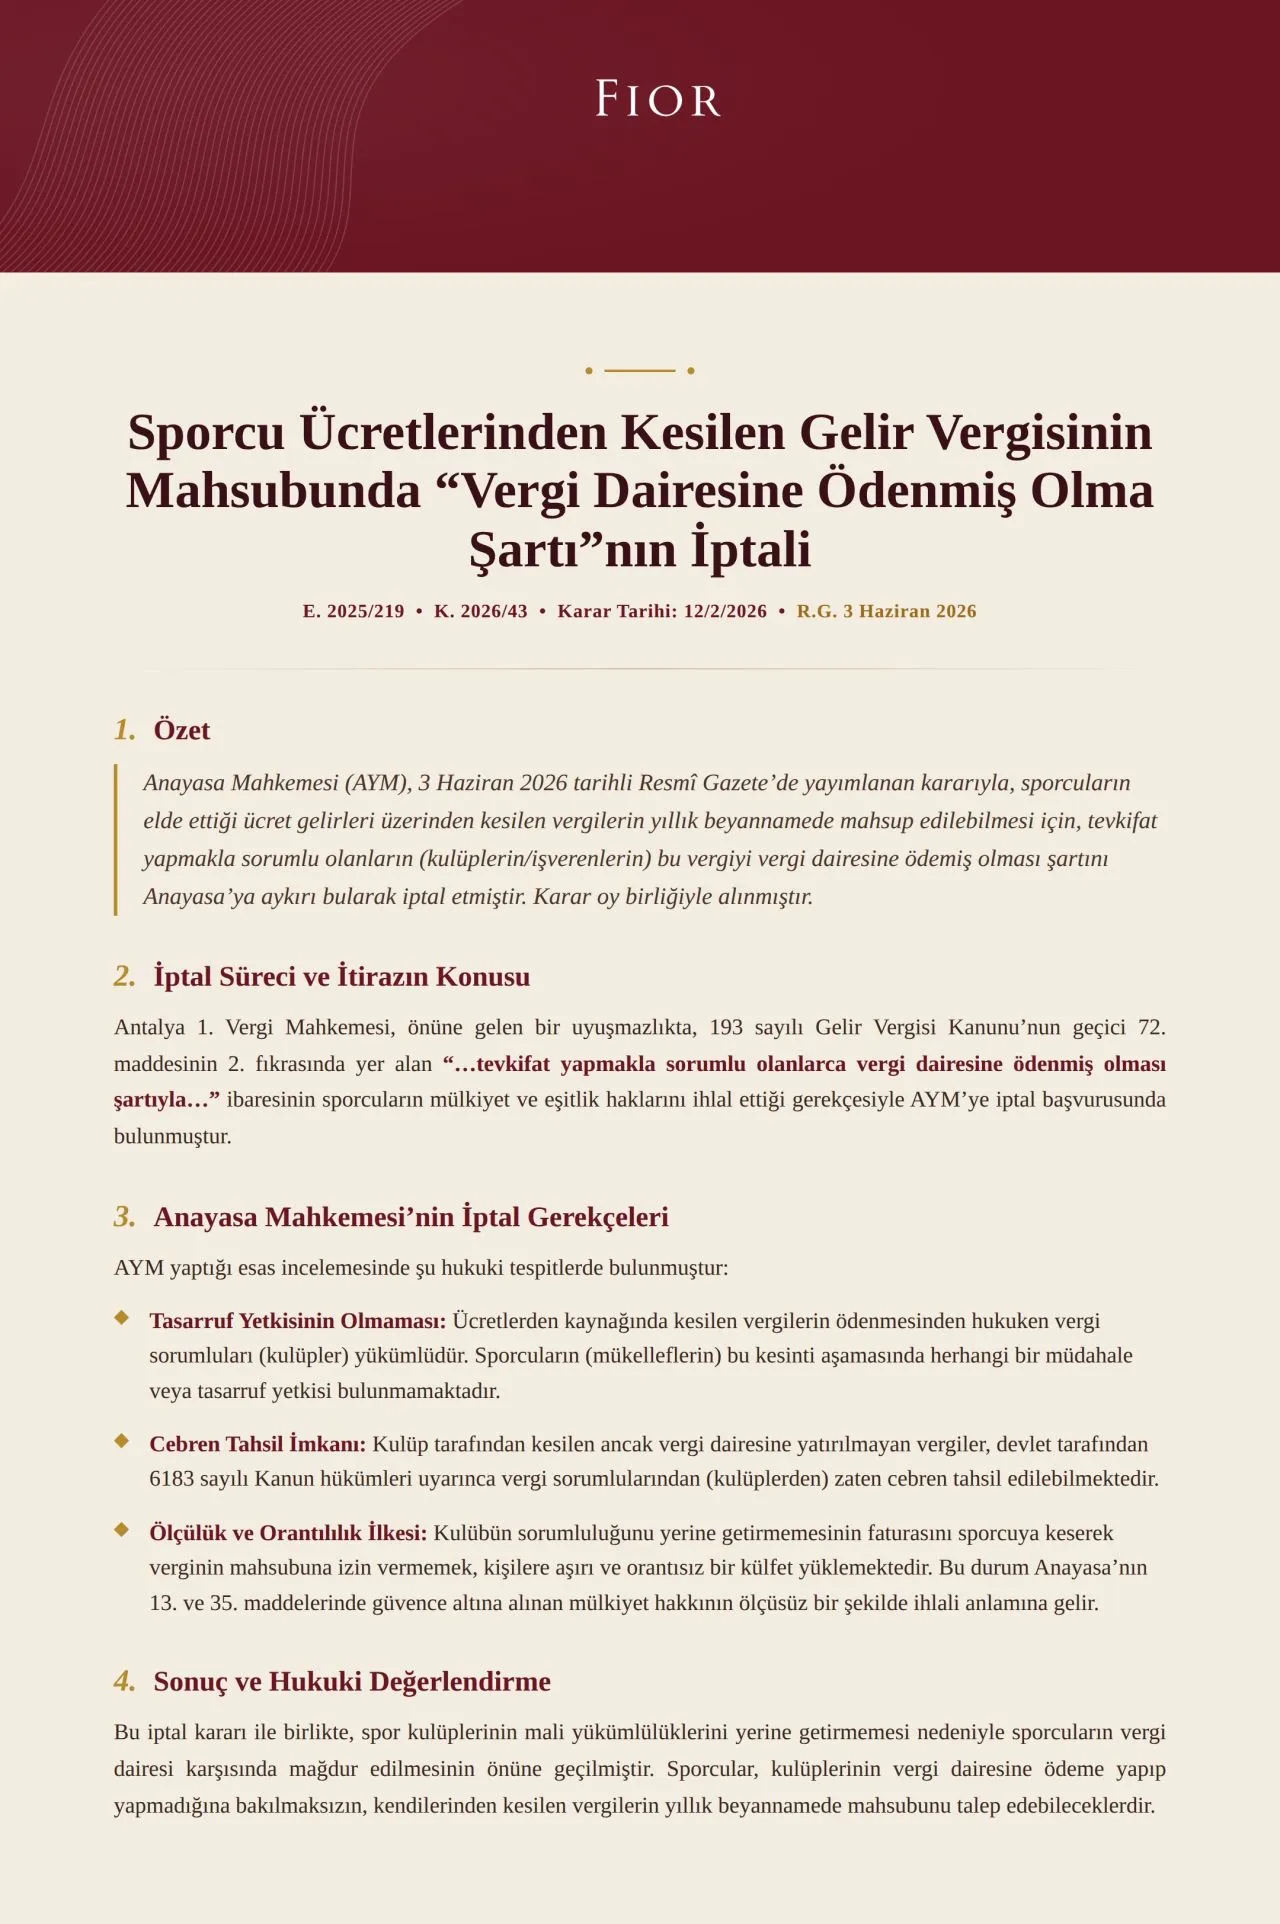
The Constitutional Court (E. 2025/219, K. 2026/43) unanimously annulled the condition that, for income tax withheld from athletes’ wages to be offset on the tax return, “the tax must have been paid to the tax office”.
The reasoning is clear: the obligation to remit withholding tax sits with the club; the athlete has no power of disposition at that stage. The State can already recover unpaid tax from the club by force. Loading the club’s fault onto the athlete is a disproportionate burden on the right to property.
Athletes may now claim the offset of taxes withheld from them even if their clubs have not made payment.
We share the full assessment of the decision in the visual.